
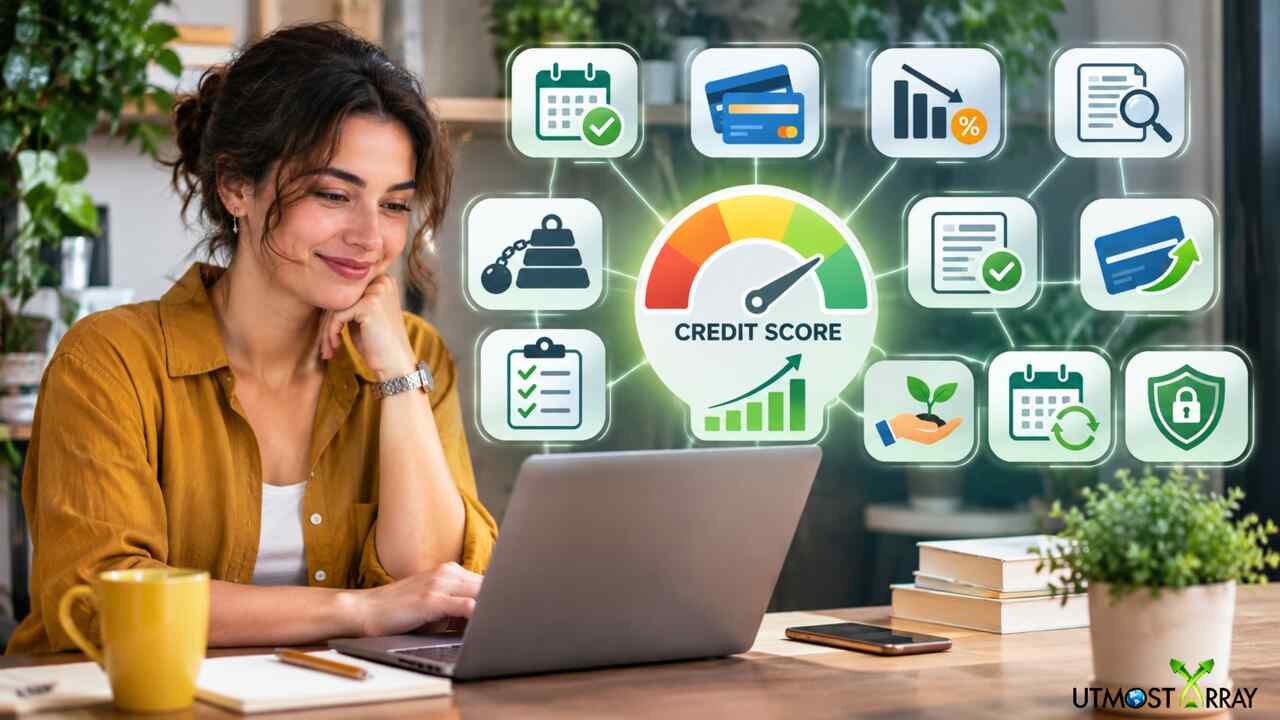
Improving your credit score starts with paying your bills on time, reducing credit card balances, checking your credit reports for errors, and managing credit responsibly. If you’re wondering how to improve credit score quickly and effectively, focus first on payment history and credit utilization because these factors have the greatest influence on commonly used credit scoring models.
Understand How Credit Scores Work and What Affects Them
Your credit score is a three-digit number that helps lenders evaluate how reliably you manage borrowed money. Most widely used FICO Scores range from 300 to 850, with higher numbers generally indicating lower credit risk.
In the United States, lenders commonly use FICO Scores, although VantageScore is another established scoring system. Your score may differ depending on the scoring model, credit bureau, and date the information is updated.
Understanding the factors behind your score helps you prioritize actions rather than spending money on unnecessary credit repair products.
What Are the Five Main Credit Score Factors?
FICO organizes credit information into five major categories. Their typical relative importance is shown below.
| Credit Score Factor | Typical FICO Weight | What It Measures |
| Payment history | 35% | On-time and missed payments |
| Amounts owed | 30% | Debt levels and credit utilization |
| Length of credit history | 15% | Age of your credit accounts |
| New credit | 10% | Recent applications and accounts |
| Credit mix | 10% | Experience with different credit types |
These percentages are general guidelines for FICO scoring, not fixed calculations that apply identically to every person or scoring model.
myFICO+1
Payment history and amounts owed deserve particular attention because they represent the largest portions of a typical FICO Score.
What Is Considered a Good Credit Score in the U.S.?
For commonly used base FICO Scores, the general credit score ranges are:
- 300–579: Poor
- 580–669: Fair
- 670–739: Good
- 740–799: Very good
- 800–850: Exceptional
A score of 670 or higher is generally considered good, but individual lenders establish their own approval requirements.
For example, someone with a 690 credit score may qualify for financing but receive different interest rates than someone with a 780 score. Your income, debt-to-income ratio, employment, and other financial details may also affect approval decisions.
Pay Bills on Time to Build a Strong Payment History
Paying every credit account on time is one of the most effective ways to improve your credit score. Payment history represents approximately 35% of a typical FICO Score, making consistent payments especially important.
A late payment reported to a credit bureau can remain on your credit report for up to seven years. However, its impact may diminish over time as you establish more positive payment behavior.
The most important habit is simple: make at least the minimum required payment by its due date, every month.
How Can Automatic Payments Prevent Credit Damage?
Setting up automatic payments can protect you from forgetting due dates, especially when you manage several credit cards or loans.
For example, imagine you have three credit cards with payments due on different days. Instead of remembering each date, you could schedule automatic minimum payments and make additional payments manually.
This approach helps avoid accidental missed payments, provided your checking account has sufficient funds.
You can also request that card issuers move payment due dates closer to your payday. Remember that autopay still requires monitoring to prevent overdrafts or failed payments.
What Should You Do If You Already Missed a Payment?
If you miss a payment, contact your lender immediately and bring the account current as soon as possible.
Many creditors generally report late payments once an account reaches 30 days past due. However, late fees or penalty terms may apply earlier.
If you have previously maintained a good payment record, you can politely request a late-fee waiver or ask whether the lender offers a one-time courtesy adjustment. Approval is not guaranteed.
If financial hardship caused the missed payment, ask about hardship programs, modified payment arrangements, or temporary assistance.
Getting current prevents additional late-payment problems from accumulating, even when a legitimate past delinquency remains on your credit report.
Lower Credit Utilization to Improve Your Score Faster
Reducing credit card utilization is often one of the fastest ways to improve your credit score, particularly when your cards currently carry high reported balances.
Credit utilization measures how much revolving credit you’re using compared with your available credit limits.
For example, if you have a $5,000 credit limit and a $2,000 balance, your utilization rate is 40%.
Although keeping utilization below 30% is a commonly recommended starting point, lower utilization can be better. There is no universal percentage that guarantees a particular score.
How Do You Calculate Your Credit Utilization Ratio?
Consider a simple example with a $10,000 total credit limit:
| Reported Balance | Credit Utilization | Practical Interpretation |
| $8,000 | 80% | Very high utilization |
| $5,000 | 50% | High utilization |
| $2,500 | 25% | Below the common 30% guideline |
| $900 | 9% | Low utilization |
| $0 | 0% | No reported revolving balance |
These are illustrative utilization levels, not guaranteed score outcomes. Scoring models can consider both overall utilization and utilization on individual cards.
If your utilization is currently 80%, lowering it to 25% could help your score once the updated balance appears on your credit reports.
Should You Pay Before the Statement Closing Date?
Paying your credit card before its statement closing date may help reduce the balance reported to the credit bureaus.
Most card issuers report account information periodically, often around the statement date, although reporting schedules vary.
Suppose you spend $1,500 on a card with a $3,000 limit. Paying $1,200 before the balance is reported could leave a reported balance of $300, representing 10% utilization.
The important distinction is that the statement closing date and payment due date are different.
Paying the full statement balance by the due date generally avoids purchase interest when your grace period applies. You do not need to carry interest-bearing debt to build credit.
Check Your Credit Reports and Correct Inaccurate Information
Reviewing your credit reports is an essential step because inaccurate information can unnecessarily damage your credit score.
The three major U.S. credit bureaus are Equifax, Experian, and TransUnion.
Each bureau may receive slightly different account information, which can produce differences among your credit reports and scores.
You can access free weekly reports from all three bureaus through AnnualCreditReport.com. Checking your own credit report does not hurt your score.
What Credit Report Errors Should You Look For?
When reviewing your reports, pay particular attention to incorrect account details and payment records.
Common problems include accounts you don’t recognize, payments incorrectly marked late, inaccurate balances, duplicate collection accounts, and debts that should no longer appear.
For example, suppose your report incorrectly identifies a mortgage payment as 60 days late even though you paid it on time. Correcting that information could improve your score if the inaccurate entry was affecting it.
Save payment confirmations, account statements, and relevant correspondence to support any dispute.
How Do You Dispute Credit Report Errors?
You can dispute inaccurate information directly with the credit bureau displaying the error. You should also contact the company that supplied the information.
Explain what is incorrect, identify the account, and provide supporting documents.
Credit bureaus generally must investigate disputes within 30 days, although certain circumstances allow up to 45 days.
After the investigation, check whether the information was corrected.
Disputing errors is free, and you do not need to hire a credit repair company. Accurate negative information generally cannot be removed simply because you dispute it.
Build Positive Credit History Without Taking Unnecessary Debt
If you have a limited credit history or previously struggled with payments, establishing new positive credit activity can support long-term improvement.
The key is choosing an affordable credit-building method that reports your payment activity to major credit bureaus.
You don’t necessarily need a traditional unsecured credit card. Secured cards, credit-builder loans, and certain rental reporting programs may help, depending on your circumstances.
However, opening multiple unnecessary accounts can create costs and potentially hurt your score temporarily.
Can Secured Credit Cards and Credit-Builder Loans Help?
A secured credit card usually requires a refundable security deposit that helps establish your credit limit.
For example, you might deposit $300 and receive a $300 credit limit. Using the card for small purchases and paying the statement balance in full can help establish payment history.
Some banks and credit unions also offer credit-builder loans. These typically involve making payments while the loan proceeds are held in a restricted account until specified conditions are met.
Before choosing either option, check its fees, interest charges, reporting practices, and repayment terms. A credit-building product is most useful when it is affordable and reports to the bureaus relevant to your goals.
Can Rent Payments and Authorized User Accounts Improve Credit?
Certain rent-reporting services can add eligible housing payment information to credit reports. However, not all credit scoring models use rental information in the same way.
Before paying for a service, verify which bureaus receive the information and whether the service reports late payments.
Becoming an authorized user on someone else’s credit card may also help if the issuer reports the account and its history is favorable.
For instance, being added to a relative’s established card with a low balance and consistent payments could strengthen your credit profile.
However, high utilization or missed payments on that account could create problems. Authorized-user benefits also vary among scoring models.
Protect Your Credit History and Avoid Common Score-Lowering Mistakes
Improving your credit score is not just about adding positive information. You must also avoid decisions that unnecessarily weaken your existing credit profile.
A common mistake is closing an older credit card immediately after paying off its balance. Closing a card can reduce your available credit and increase utilization.
Another mistake is applying for several new credit products within a short period, potentially creating multiple hard inquiries and lowering the average age of your accounts.
Making borrowing decisions based on actual financial needs is generally better than opening accounts solely to chase a higher score.
Does Closing an Old Credit Card Hurt Your Score?
Closing an old credit card can affect your score, but the impact depends on your overall credit history.
Consider someone with two credit cards, each carrying a $5,000 limit, and a combined balance of $2,000.
Their total credit utilization is 20%. If they close one unused card, the utilization rate could increase to 40%, assuming the full $2,000 balance remains on the other card.
Closed accounts in good standing can remain on credit reports for years and may continue contributing to credit history length.
Keeping an old no-annual-fee account open can be worthwhile, provided you can manage it responsibly. If the card has expensive fees or encourages overspending, closing it may still make financial sense.
How Do Hard Inquiries and New Credit Applications Affect Your Score?
A hard inquiry generally occurs when a lender reviews your credit report as part of a financing application.
A single inquiry usually has a relatively small effect, but several unrelated applications close together can raise concerns.
By contrast, checking your own score or report is a soft inquiry and does not lower your credit score.
When shopping for an auto loan, mortgage, or certain student loans, eligible inquiries made within a scoring model’s rate-shopping window may be treated as one for scoring purposes. The applicable window varies by model.
Avoid applying for credit you don’t need, especially shortly before seeking a mortgage or another major loan.
Create a Realistic Credit Improvement Plan and Track Your Progress
The best way to improve your credit score consistently is to combine several habits into a manageable financial routine.
Rather than expecting a specific number of points in a few days, focus on actions that address the weaknesses in your credit report.
If your score is low because of high credit card balances, reducing utilization may produce relatively quick changes. If it is low because of serious delinquencies, improvement generally requires more time and consistent payments.
Your progress also depends on when lenders update your credit reports and which scoring model you monitor.
What Should You Do During Your First 30, 60, and 90 Days?
A structured 90-day plan can make the process easier.
Days 1–30: Establish your starting point
Obtain your credit reports, identify inaccuracies, list debts and due dates, enable autopay, and determine which balances you can reduce safely.
Days 31–60: Reduce credit risk
Continue paying on time, prioritize high-utilization credit cards, submit supported disputes, and avoid unnecessary credit applications.
Days 61–90: Review and adjust
Check updated credit reports, compare reported balances, confirm dispute results, and adjust your repayment plan based on measurable progress.
The 90-day period is a planning framework, not a promise of improvement. Significant negative information may require a longer rebuilding period.
How Can You Maintain an Excellent Credit Score Long-Term?
Maintaining strong credit requires consistency rather than complicated financial techniques.
Continue paying bills on time, keep revolving balances manageable, and review your accounts regularly. Maintain an emergency fund when possible so unexpected expenses are less likely to cause missed payments.
You can also request credit limit increases from existing issuers, but first ask whether the request involves a hard inquiry. A higher limit may reduce utilization only if you avoid increasing spending.
Most importantly, remember that a credit score is only one measure of financial health. Avoid unnecessary interest, fees, and borrowing simply to increase it.
Conclusion
Learning how to improve credit score comes down to understanding what affects your credit and developing responsible financial habits. Paying bills on time, lowering credit utilization, correcting reporting errors, and maintaining established accounts are among the most effective strategies.
Although some changes may appear relatively quickly, meaningful credit improvement often requires patience and consistent financial behavior. Avoid companies promising guaranteed score increases, and never borrow unnecessarily just to build credit.
Your best next step is to review all three credit reports, identify the factors holding your score back, and create a realistic repayment plan. Consistent progress can strengthen your credit profile and improve future borrowing opportunities.
FAQs
How long does it take to improve your credit score?
You may see improvements within one or two reporting cycles after reducing credit card balances or correcting significant errors. Rebuilding a score affected by late payments, collections, or other serious negative information may take several months or years. The exact timeline depends on your credit profile, updated reporting information, and scoring model.
How can I raise my credit score by 100 points?
A 100-point increase may be possible for some credit profiles, but it cannot be guaranteed. Start by correcting inaccurate negative information, bringing overdue accounts current, reducing high credit utilization, and establishing consistent on-time payments. The potential improvement depends heavily on why your score is currently low. No legitimate method guarantees a specific point increase.
Can I improve my credit score without a credit card?
Yes. You may build credit through installment loans, certain credit-builder loans, and eligible rent-reporting programs. Making timely payments on accounts that report to credit bureaus can help establish a positive history. However, having no revolving credit accounts may limit certain aspects of your credit profile, depending on the scoring model.
Does paying off debt immediately increase your credit score?
Paying down credit card debt may improve your score after the lender reports the lower balance. Paying off an installment loan may have a different effect, and sometimes your score can temporarily decrease after the loan closes. Paying debt remains financially beneficial because it can reduce interest expenses and improve your overall financial position.
Is it possible to improve a 500 credit score?
Yes. A 500 credit score can improve through responsible financial management, although the process may take time. Focus on preventing additional missed payments, addressing overdue accounts, reducing credit card utilization, and reviewing reports for inaccuracies. Secured credit cards or affordable credit-builder products may also help establish positive activity when used responsibly.
Does checking your credit score lower it?
No. Checking your own credit score or requesting your credit report is considered a soft inquiry and does not hurt your score. You can monitor your credit through certain banking apps, credit card issuers, and credit monitoring services. Be aware that scores from different providers may vary because they use different scoring models or credit bureau data.
